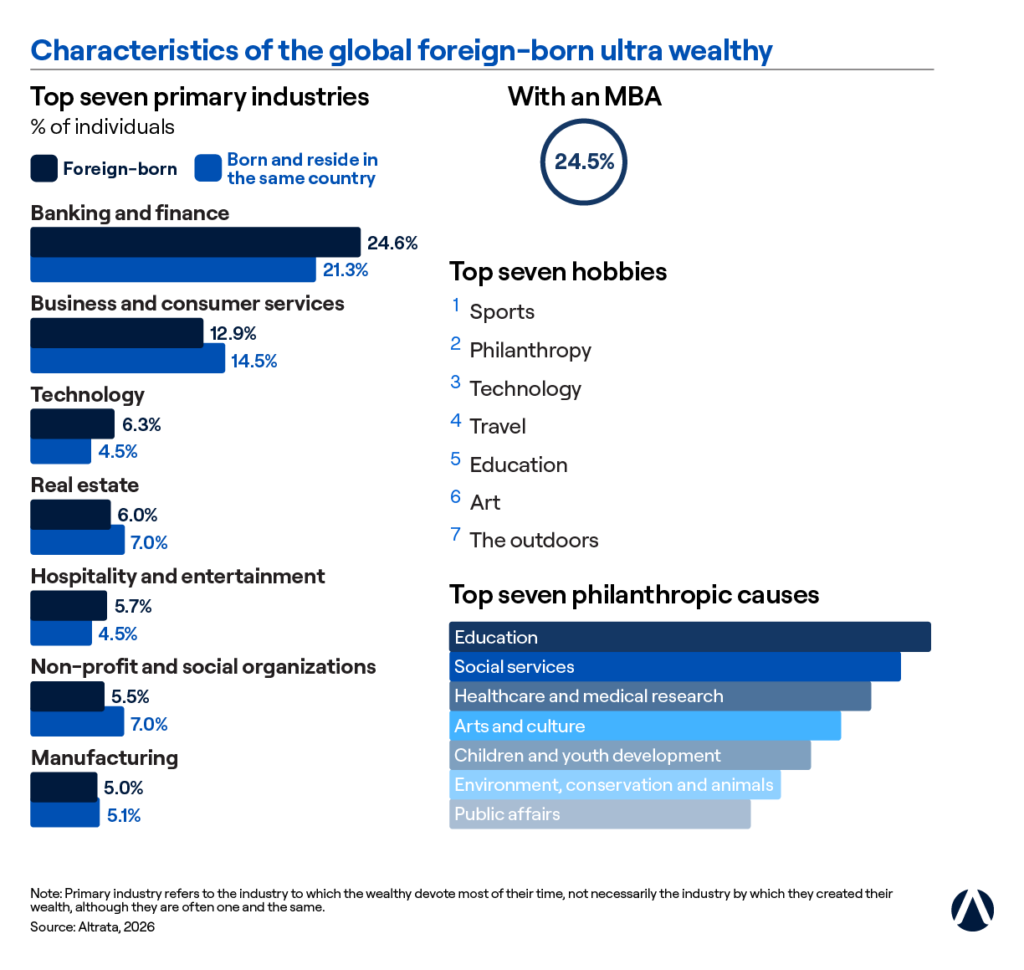
When we think of wealth, we often picture stacks of cash in a vault or a simple checking account with a seven-figure balance. However, for the truly affluent—the billionaires and ultra-high-net-worth individuals (UHNWIs)—the banking system they use looks radically different from the one used by the average person. In fact, many of the banks you and I rely on are the institutions they avoid.
The core reason is simple: The rich don’t use traditional banking for wealth accumulation; they use it for logistics. If you ask the question, “Where do billionaires keep their money?” the answer rarely includes a standard savings account or a neighborhood bank branch.
Here is the inside look at why the rich don’t use savings accounts and the specific types of banks rich people avoid like the plague.
The “Savings Account” Myth: Why 0.01% APY Is a Losing GameThe most common mistake the middle class makes is viewing a savings account as a wealth-building tool. The ultra-wealthy view it as a guarantee of loss.
Source: www.instagram.com
Why the rich don’t use savings accounts:
- Inflation Erosion: With inflation averaging 2–3% annually (and often higher), a savings account paying 0.01% to 4% APY is a guaranteed loss of purchasing power. A billionaire would never park $100 million in a savings account to watch it lose $2 million in real value every year.
- Opportunity Cost: Every dollar in a savings account is a dollar not invested in assets that appreciate—stocks, real estate, private equity, or art. The rich view cash as a “dry powder” asset that should be deployed, not stored.
- Liquidity Overload: Savings accounts are designed for liquidity (easy access). The ultra-wealthy don’t need immediate access to their entire net worth. They keep 1–2% of their wealth in liquid cash for living expenses; the rest is working for them in illiquid, high-return assets.
Where do billionaires keep their money instead?
Billionaires keep their wealth in a diversified portfolio of hard assets and capital appreciation vehicles:
- Public Equities & Bonds: Managed through brokerage accounts, not banks.
- Private Equity & Hedge Funds: Direct investments that offer returns far exceeding inflation.
- Real Estate: Tangible assets that hedge against inflation.
- Art, Yachts, and Collectibles: Assets that appreciate over time (and are often used as collateral for loans).
- Their Own Companies: Most billionaires have their net worth tied up in the stock of the business they founded.
The key financial vehicles they use are cash value life insurance (such as a permanent life insurance policy) or family offices—private wealth management firms that act as their personal bank, investing their assets across global markets.
The Banks Rich People Avoid (The Red Flags)
Source: www.amazon.com
Not all banks are created equal. The ultra-wealthy avoid specific types of banks because they fail to provide the three core needs of a billionaire: privacy, credit, and tax efficiency.
A) The “Big Box” Retail Banks (e.g., Wells Fargo, Bank of America, Chase)
Source: www.facebook.com
Why they are avoided: These banks are built for mass-market retail banking. They are heavily regulated, have low deposit limits, and are notorious for freezing accounts for “suspicious activity.” A billionaire moving $50 million is going to trigger endless compliance questions. Furthermore, these banks offer terrible lending rates for the ultra-wealthy. A high-net-worth individual can get a loan at the Secured Overnight Financing Rate (SOFR) + 1% from a private bank. A retail bank will charge them the prime rate (8%+).
B) Online-Only “Neobanks” (e.g., Chime, Revolut, N26)
Why they are avoided: These are great for fee-free spending and budgeting, but they are a nightmare for large sums. They have strict withdrawal limits, limited asset management, and zero privacy. Billionaires need a human relationship manager, not a chatbot.
C) Credit Unions
Why they are avoided: While excellent for local communities, credit unions lack the global infrastructure, international wire capabilities, and massive credit lines needed by the wealthy. A billionaire cannot get a $100 million mortgage or a complex margin loan against their stock portfolio from a local credit union.
So, Where Do the Rich Bank? The Secret World of Private Banking
Instead of retail banks, the ultra-wealthy use private banks and family offices.
The Giants of UHNW Banking:
J.P. Morgan Private Bank – Not the Chase you see on the corner. This is a separate, exclusive division for clients with $10 million or more.
- Goldman Sachs Private Wealth Management – The “House of Goldman.” They require $10 million to $25 million to open an account.
- UBS Global Wealth Management – The largest wealth manager in the world, with a stronghold in Europe and Asia.
- Citi Private Bank – Known for “relationship lending” and complex credit structures.
- Boutique Firms (e.g., Brown Brothers Harriman, Rockefeller Capital Management)
What makes them different?
- “Banking as a Service”: The wealthy use loans, not their own cash. A billionaire might buy a $50 million yacht. They don’t sell stock and pay capital gains tax. Instead, they go to their private banker, pledge the stock as collateral, and take out a “portfolio loan” at 2% interest. The stock continues to grow, the interest is deductible, and they never realize a taxable gain.
- Asset Allocation: The private bank acts as a Chief Investment Officer, managing a custom portfolio of global stocks, bonds, private equity, hedge funds, real estate, and direct investments.
- Privacy: These banks are masters of confidentiality. They operate in secrecy jurisdictions (Switzerland, Singapore, Cayman Islands) to protect client identity from lawsuits, prying family members, and tax authorities (legally, through trusts and shell companies).
- Concierge Services: Need a private jet to Monaco at midnight? Want to buy a vineyard in Tuscany? The private banker handles it. They function as a personal CFO, not a teller.
The “Rich Person’s Secret Account”: Why They Use Bank Loans Like Debit Cards
This is the most counterintuitive part of understanding where do billionaires keep their money.
The Strategy: The rich are often “poor” on paper in terms of liquid cash. They keep their money in appreciating assets (stocks, real estate). To spend money, they borrow against those assets, not sell them.
Why this is genius:
- Zero Capital Gains Tax: You don’t pay tax on a loan. A billionaire can borrow $10 million, spend it on a mansion, and the stock he used as collateral continues to grow.
- “Buy, Borrow, Die”: When the billionaire dies, their heirs inherit the assets with a “stepped-up basis” (the cost basis resets to the current market value). The loans are repaid from the estate, and the family pays zero capital gains tax.
This is why they avoid savings accounts. A savings account generates taxable interest income. A loan from a private bank provides non-taxable liquidity.
Conclusion: The Bank You Should Avoid (for Wealth Building)
If you want to think like the wealthy, you need to shift your mindset.
The biggest trap is keeping too much cash in a traditional savings account or a big retail bank. The wealthy avoid these because they are financial “drains.” You cannot build a fortune by earning 0.01% interest on your cash.
Instead, adopt the “billionaire mindset”:
- Use debt strategically. Don’t be afraid of good debt (low-interest, asset-backed).
- Park your emergency fund in a high-yield savings account or money market fund (at least 4%+ yield).
- Invest the rest. Your money must be working harder than inflation.
- Find a private client relationship. Even if you aren’t worth $10 million, many private banks have “Premium” or “Private Client” tiers with better rates and personalized service for accounts over $250,000.
In the end, the secret isn’t where the rich hide their money—it’s that they never let it sit still. And they certainly never let it rot in a savings account.