For luxury brands, high-end lenders, and premium asset managers, the definition of the target demographic is undergoing a rapid evolution. The ranks of “super prime” consumers—those holding top-tier credit scores above 780—have expanded by 15 million individuals over the last six years.
Driven by an affluent, highly financially literate younger demographic, this surge is reshaping how financial institutions distribute premium credit cards, wealth products, and high-limit capital lines.
The Demographics of Premium Credit
Historically, the most elite credit tiers were dominated by older, established wealth. Today, a significant portion of this growth is powered by Gen Z and Millennial consumers who view credit health as a strategic asset.
Major financial institutions are actively pivoting their acquisition strategies to court this rising class of high-end spenders:
- American Express: Reports that Gen Z and Millennial account acquisitions continue to outpace older generations in key credit metrics, with the vast majority of new accounts opting for premium, fee-paying products.
- Citigroup: Notes its portfolio remains heavily weighted toward prime consumers, with approximately 85% of its balances extended to consumers with a FICO score of 660 or higher.
- Asset Growth Catalyst: The entry of 15 million new consumers into the super prime category was heavily accelerated by pandemic-era savings, rising worker incomes, and a prolonged surge in both the stock market and home values.
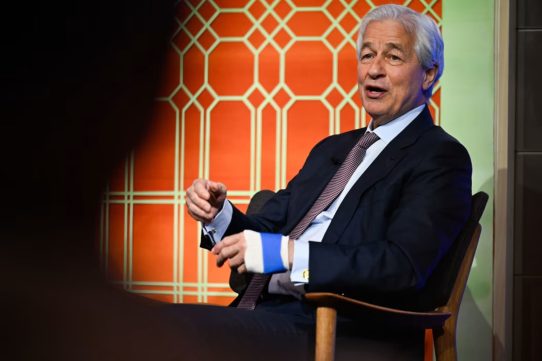
“The younger generation is more equipped for changing financial dynamics than prior generations. I feel much more comfortable having a card base that skews younger than what we saw a decade ago.”
— Stephen Squeri, CEO of American Express
The Bifurcated Economy: A Tale of Two Consumers
While the aggregate data paints a picture of a resilient consumer base, wealth managers are keeping a close eye on an increasingly divided economic landscape. The spending power driving the premium economy is heavily concentrated within the upper-middle class and high-net-worth brackets, where income growth has comfortably outpaced inflation.
Beneath this prosperous surface, structural friction is emerging:
| Credit Tier | Market Trend (Past 6 Years) | Average Credit Line Limits |
| Super Prime (780+) | Expanded to over 41% of consumers with a balance | Increased 11% |
| Near Prime / Subprime | Remaining flat, with credit-card debt hitting a record $1.3T | Increased only 5% |
This divergence means lenders are tightening risk parameters on the lower end—capping credit limits and managing rising auto-loan and foreclosure risks—while simultaneously competing to offer unprecedented credit lines and bespoke rewards to the super-prime tier.
The Meridian Verdict
For the luxury market, the inflation of the super-prime club is highly lucrative intelligence. The consumer base eager to acquire high-end goods, premium travel experiences, and elite financial services is younger, highly credit-conscious, and holds greater borrowing capacity than ever before. For brands and wealth managers alike, capturing this cohort early is no longer a future strategy—it is the current baseline for sustained luxury market growth.
Stay tuned to Luxury Meridian for ongoing insights into the wealth trends redefining the global marketplace.
Was looking for The Bifurcated Economy and i found what i was looking for thanks